adel
- Home /
- Author's Archive:
ITV’s turn to buy into the de Mol format dream
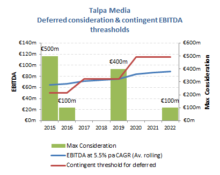
The story is an old one. Broadcaster facing erosion of its distribution monopoly buys successful production business to supplement the lack of creative output from its own in-house content origination arm. Whether it was TVS’s purchase of MTM, Thames TV’s acquisition of Reeves or Pearson’s serial offending with Grundy and then All American, the narrative […]
Continue readingYahoo unveils ‘SpinCo’. Well it can’t be plainer than that surely?

Yahoo Inc: New management has finally accepted what the markets have been trying to discount for some time; that with Jerry Wang’s legacy investments in Alibaba and Yahoo Japan, Yahoo was beginning to look like an investment trust. New CEO, Marissa Marr’s decision to split off the remaining (15.4%) stake in Alibaba into a new […]
Continue readingTesco: Phase 2 – reset investor expectations

It’s always entertaining to see good people-management at work. As with a new Government, a new management needs to persuade the stakeholders that their predicament is substantially worse than previous team were letting on, but that with a little pain, the new team and plan (usually with a catchy name) will secure recovery by the […]
Continue readingEnterprise Inns: Asset play or just value trap?
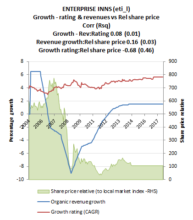
Enterprise Inns (ETI): With a share price at an almost 60% discount to NAV, this may appear to be a compelling asset play, albeit this argument might have also appeared valid when the discount was 30%,40% or 50%. As with banks in 2008, a balance sheet asset is only as good as the credibility it […]
Continue readingNovember non-farm payrolls – Bah Humbug!

I can hardly contain myself with excitement. US non-farm payroll data for November is out and the headlines are that the +321k MoM additions (+314k for the more relevant Private sector jobs) “smashes forecasts†(Guardian) and that “The dollar has gone through the roof†(City AM). With another month of unemployment at only 5.8% (try […]
Continue readingAirlines and oil prices

With fuel costs representing 45-50% of an airline’s operating costs and 35% of its revenues, it would seem self-evident that a significant movement in oil, and therefore fuel prices, would have an equally dramatic effect on margins; in particular when the industry’s margins are often the wrong side of 5%. The oil price however is […]
Continue readingP&G swaps Duracell at 7x EBITDA for shares in itself at 13x. Buffet wins again!
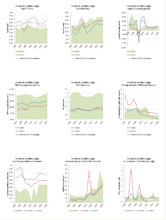
When a company such as P&G can sell 10 year debt at little more than a 3% coupon, then we should not be surprised at some of the pricing decisions being taken. With regards its subsidiary Duracell, it has a business in slow structural decline, which provides a drag to its own organic growth figures, […]
Continue readingITV – Onus on content delivering the goods as NAR growth slows and audience share erodes

New management with a new veneer to the content strategy and a cyclical recovery in UK TV advertising have all encouraged markets to give ITV the benefit of the doubt that this time it can manage the transition from distribution monopolist to a more balanced content origination and distribution business, albeit in a considerably more […]
Continue reading