adel
- Home /
- Author's Archive:
Digital Plonkers

WPP’s annual digital investor day provided Sir Martin Sorrell another opportunity to show off his digital wares as well as take some entertaining swings at rivals; particularly the “plonkers†who had recently been over-paying (ie out-bidding WPP) for digital assets and particularly those in Brazil. Comment est-ce qu’on dit ça en Francaise Maurice? At […]
Continue readingRecency bias – the curse of financial markets!
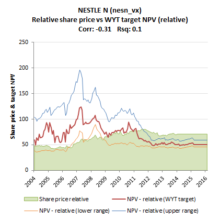
We are all guilty of it, but it is probably the single most dangerous investment sin. Perhaps it is part of our social evolution to conform. A sort of “Eat shit 17 quadrillion flies can’t be wrongâ€. With regards to financial markets you may have seen the same shit, but given a pseudo- intellectual […]
Continue readingPublicis bids $3.7bn for Sapient Inc. – how to buy ‘organic growth’

Finding a marriage of ‘equals’ with Omnicom was not to its tastes, Publicis is back to what it does best; hoovering up smaller digital marketing operations. When you are not a Wonga client and can borrow at only 2.6%, then buying in a business on an operating profit yield of approx 5.5% before synergies and […]
Continue readingMarkets find it tough to break the BTFD conditioning
Was the Friday rebound in equity markets another BTFD opportunity, or a possible suckers rally? Certainly, the wall of central bank liquidity over the past five years have reduced the market’s pricing mechanism to little more than a pavlovian response to the next turn of the central tap and where bad news can be good […]
Continue readingBudget airlines soar in September, but war of the handbags still being fought
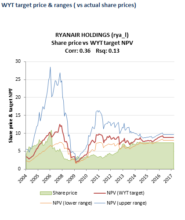
Ryanair is still packing in the passengers (Sept +5% with load +5ppts to 90% vs +7.5%/+2.5ppts respectively for EasyJet), although with the Air France strike settled and the end of the summer holiday season I would expect the Oct traffic figures to be a little less supportive. The stock is still my preferred one in […]
Continue readingBeware fake arbitrages on Yahoo – Alibaba!

For an arbitrage opportunity to exist, asset classes need to be fungible (deliverable against each other), so anyone selling you a scheme to “arbitrage” an apparent pricing disparity between related, but non-fungible, assets maybe selling you a dud. When I see investor research by banks, who should know better, promoting “the Yahoo arbitrage trade” […]
Continue readingIPO: Market valuing Alibaba as if it were a normal US tech Co!

I am surprised! Having cleaned up the reported numbers a little (eg including stock comp and intangible amortisation – excl goodwill), and applied a broadly average growth discount trend, the Alibaba NPV on the WYT growth discount model comes within 5% of the post IPO price – nb this already adjusts for forward valuation horizon […]
Continue readingFinally, a memorable financial advert
With marketing infatuated with big data, social media, mobile and any other nerdy technology where they can bamboozle the client with techno-babble, it is a pleasure to see a good creative advert. I may have been ‘exposed’ to a thousand marketing messages from the financial services industry, and for which someone has paid good money, […]
Continue reading