adel
- Home /
- Author's Archive:
Trump’s oil supply leverage
It says a lot for either the weak outlook for global GDP growth or the limited threat posed by the Iranians, that a series of attacks and seizures of oil tankers in the Straits of Hormuz, a conduit for around 20% of the world’s oil needs, as had no appreciable impact on crude oil prices. […]
Continue readingWeak job growth? Just fiddle the seasonal adjustments!
How can the Fed contemplate cutting rates when US Q1 GDP growth allegedly came in at over +3% and June saw a +224k MoM rise in employment? Perhaps because it knows these headline numbers are garbage and that the true underlying numbers are considerably worse than these. Having already commented on the fiddles used to […]
Continue readingLies, damn lies and Govt statistics
On Friday 25th the US will report its advance estimate for Q2 GDP growth, although the main point of interest may again be the how the numbers have been doctored to fit a political narrative. Back on 5 May, we highlighted the way in which the Q1 growth estimate of +3.2% had been overstated and […]
Continue readingGold returns
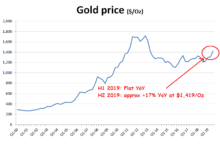
Was it the flip-flopping Federal reserve or Draghi’s increasingly desperate attempts to reflate the ECB debt balloon, but with Iran scare stories it has done wonders for the gold price. While forthcoming Q2 results will be pretty drab for the industry, with H1 average prices broadly flat YoY, the second half is on track for […]
Continue readingUS job growth stalls – a more reliable indicator than initial GDP
Well, well, once again the monthly non-farm payroll numbers provide the insight on the real state of the US economy. As with 2008, forget the official GDP numbers, or at least the initial ones. Forget also the the spin from those with an interest to persuade you everything is dandy, particularly those encouraging you to […]
Continue readingFCA-Renault merger crash tested by dummies
With the auto industry facing some existential challenges, one might have thought a low margin operator and its shareholders would have seized at the opportunity for a highly synergistic merger. Unfortunately, when one of those shareholders is the French Government, then the normal commercial rules don’t seem to apply. So after some foot-dragging by Macron […]
Continue readingZero bond yields are not without a cost. Mind the Gap!
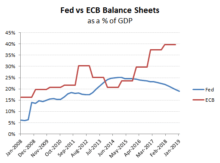
Interesting article yesterday on Bloomberg reporting that billionaire Stan Druckenmiller has dumped equities in favour of US treasuries, where he sees 10 year yields dropping to zero over the next 18 months. The two big assumptions however, is that Trump won’t get re-elected in 2020 and that US yields will converge down to those in […]
Continue readingYield curve danger signals
A flattening yield curve is often taken as a bad omen for prospective GPD growth, so according to this theory, surely the increasing divergence in rates across the maturity range is good? Hmm, well actually no, as yields also diverged, while falling in the 2-3 quarters immediately preceding the last two recessions. Perhaps horse and […]
Continue reading